Business Loans for Good Credit
If you have good credit, the world of business loans is your oyster. Business loans for good credit come with lower rates and a wider choice of lenders because a strong business loan credit score marks you out as a reliable borrower.
- Funding from £1,000 to £10 million
- Decisions in as little as 1 hour
- Compare funding options from trusted lenders
- Check your eligibility in minutes
It's fast, free and won't affect your credit score

Trusted by Hundreds of Business Owners
- What is a good credit business loan?
- Do you need good credit for a business loan?
- What’s a good credit score for a business loan?
- Types of business financing with good credit
- What can negatively affect your business credit score?
- Should I improve my credit score?
- Why choose Capalona for good credit business loans?
- Good credit business loan FAQs
Checking won’t affect your credit score
So what does good credit look like, how can you improve it, and what loan options are available if you already have it? Read on to find out.
What is a good credit business loan?
A good credit business loan is a loan you can apply for if you have good credit. A good credit score means you’re a trustworthy borrower in the lender’s eyes, which means you’re highly likely to repay the loan in full within the agreed repayment terms.
If you don’t have good credit right now, that doesn’t mean that’ll always be the case. You can take steps to improve your credit rating, such as paying bills on time and repaying your business credit card bill monthly.
Do you need good credit for a business loan?
No, not necessarily. There are plenty of loan options regardless of whether your credit score is good or bad. A good credit score means you’ll get favourable interest rates, longer payment terms, higher loan amounts, and a wider choice of lenders.
With bad credit, you can still apply for plenty of loans like secured loans (secured with collateral like property or vehicles), and you can sometimes get a guarantor to sign up to make loan repayments should you default.
What’s a good credit score for a business loan?
There’s no ‘one’ good credit score that lenders look for. It’s worth checking your credit score using the top credit reference agencies to understand your score across different platforms, as lenders might not use the one you use.
- Equifax says good business credit is anything above 75 (out of 100)
- Experian says an excellent credit score is anything above 80 (out of 100)
- CreditSafe says a ‘low risk’ score is anything above 51 (out of 100)
If your credit score comes back as good or excellent, you have good credit regardless of the agency you use to check it. It’s a good idea to check your credit score with at least one of the above agencies.
Credit scores for personal credit are scored slightly differently and are usually out of a score of up to 1,000.
Checking won’t affect your credit score
How your business loan credit score affects your options
Your business loan credit score shapes the rate you are offered, how much you can borrow, and which lenders will work with you. Businesses with a higher credit score usually see lower rates and larger offers, because lenders read a strong score as lower risk. If your score is mid-table, it is still worth comparing, as criteria vary widely from one lender to the next.
Types of business financing with good credit
With good credit, you have your pick regarding loan types, whether you’re looking for short-term or longer-term finance. Most lenders will welcome you with open arms if you’re creditworthy, as that’s what they’re looking for — reliable and trustworthy business owners who will repay on time.
Unsecured business loans
You can easily apply for an unsecured business loan with good credit. These loans are quick to apply for, and lenders judge eligibility on creditworthiness, alongside other factors like your reason for the loan, how much you want to borrow, the repayment period, and correct documentation (ID, etc.)
Use your unsecured loan to help manage cash flow, invest in new markets, or renovate your premises. Bear in mind that unsecured loans come with higher interest rates.
Long-term business loans
You can apply for a long-term business loan with good credit; you’ll have a wider range of lenders to choose from, favourable rates and terms. Because you’re seen as more trustworthy as a borrower, lenders are happier to lengthen the loan repayment period.
Longer-term business loans are great for businesses that want to borrow money over five years or more. If you’d like to spread the cost of your loan so the repayments are much smaller, a long-term loan could be a good option for you if you have good credit.
Short-term business loans
If you need funding fast, good credit makes short-term business loans easier to access, with some lenders making decisions in as little as 1 hour.
Credit cards
If you have a good credit score, lenders are more likely to offer you a higher credit limit on your business credit card. You might also be able to access a lower interest rate due to your good credit. Regularly repaying your credit card balance will also help you maintain a good credit score.
Business credit cards are useful to dip in and out of as and when you need a little extra financial support.
Revolving credit facility
Revolving credit can be handy, particularly if you just need to dip in and out of capital, whether to pay unexpected bills or to secure a great bulk-buy purchase from a supplier. With good credit, lenders might not require you to sign a personal guarantee.
What can negatively affect your business credit score?
There are a few things that can impact your credit rating, so here are four you should be aware of:
- Short or no business trading history. You don’t have a good credit history when your business is brand new or a startup. Lenders can deem newer companies as risky.
- High credit utilisation. This is when you use all or most of the credit available to you. This shows you might not be able to spend without your limits. The rule of thumb is to keep credit utilisation at around 30%. I.e., if your credit limit on your corporate credit card is £4,000, try not to spend more than £1,200 before repaying.
- Applying for credit too frequently. If you open new credit accounts and have multiple lenders carrying out hard credit checks, this can be a signal to future lenders that other providers have turned you down.
- Not making payments on time. If you don't make payments in line with your repayment plan, your credit score can be negatively affected. Even a single missed payment can lower your score, and it can stay on your credit file for up to six years, so future lenders will see it.
Should I improve my credit score?
You should always look to improve your credit score wherever possible. That means repaying loans and bills on time. Think credit card bills and business loan repayments, always paid on time. Paying these on time shows you’re creditworthy, so should you need to access business finance later down the line, you’ll be in a more favourable position.
Why choose Capalona for good credit business loans?
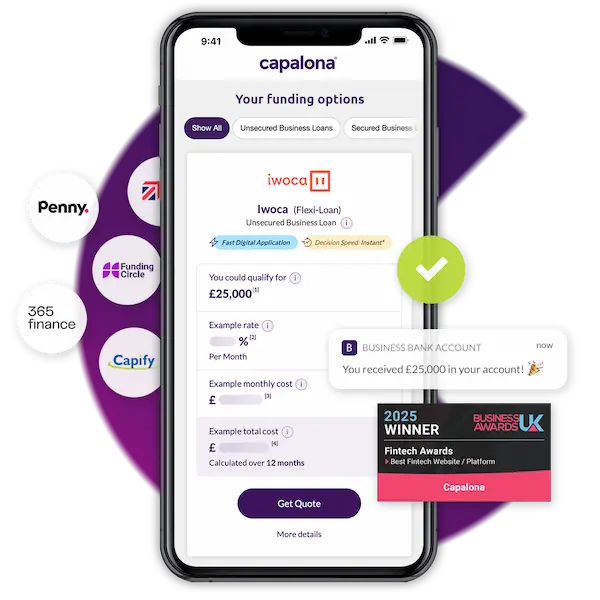
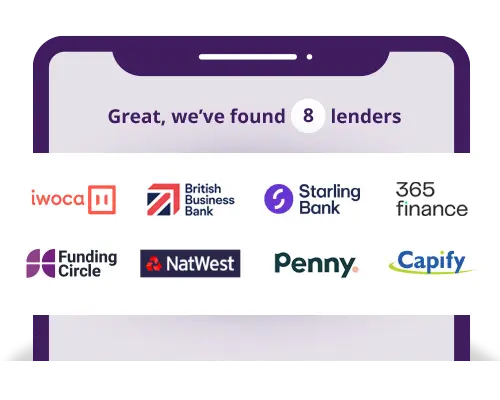
We work with many trusted UK lenders who offer flexible and affordable business loans for business owners with good credit. With so many loan types to choose from, the options can be overwhelming. That’s where we can help; our tool lets you compare lenders and suitable products instantly, for free.
Using our platform doesn’t affect your credit score, and you’re under no obligation to accept any loan deal you’re presented with.
Compare large and small business loans with good credit here.
Good credit business loan FAQs
With good credit, you’ll have a wide choice of lenders and loan types you can apply for. Simply fill in our quote form to access our free business loan comparison tool and compare eligible loans and lenders.
You don’t need to have good credit to get a business loan; there are options across the credit spectrum, but good credit can help you get lower rates, higher amounts, and a wider choice of lenders.
There is no single cutoff. Anything above 75 with Equifax, or 80 with Experian, counts as good, though every lender sets its own bar, so comparing is the fastest way to see what you qualify for.
About the author
Adrian T
5/5
Amazingly fast, efficient service, minimal paperwork. So much faster than my business bank of twelve years.


 FAQs
 0330 223 5036